Rare coins and banknotes carry financial value that often extends far beyond their original denominations. Some represent important historical events, discontinued currencies, or limited production periods. The Smithsonian Institution maintains a National Numismatic Collection containing approximately 1.6 million objects, demonstrating the historical importance of monetary artifacts. For private collectors, however, preserving these items involves financial risks. Theft, accidental damage, fires, floods, and changing market values can threaten collections accumulated over many years.
Insurance offers a way to manage some of these risks, although coverage depends on policy conditions and supporting documentation. Behind the claims process, administrative functions such as record verification, document management, and payment coordination are equally important. Insurance companies may use insurance BPO services to support these operations. Collectors can make more informed coverage decisions by understanding how valuations, insurance policies, and claims procedures work together.
Step 1: Understand What Determines Collectible Currency Values
Before purchasing insurance, collectors need a realistic understanding of what their holdings are worth. The American Numismatic Association (ANA) explains that collectible currency values depend largely on rarity, condition, supply, and collector demand.
Four factors deserve particular attention:
- Rarity: Coins and banknotes produced in limited quantities may attract greater collector interest.
- Condition: Well-preserved specimens generally command higher prices than heavily worn examples.
- Authenticity: Professional authentication helps establish whether an item is genuine.
- Market demand: Collector preferences and purchasing activity influence current prices.
Professional grading can help establish an item’s condition. However, a grading certificate does not guarantee a particular resale price. Collectors should distinguish between historical significance, estimated market value, and the amount an insurer agrees to cover.
Step 2: Obtain Appraisals and Organize Collection Records
Accurate documentation creates a foundation for appropriate insurance coverage. An outdated valuation or missing ownership record may complicate a future claim.
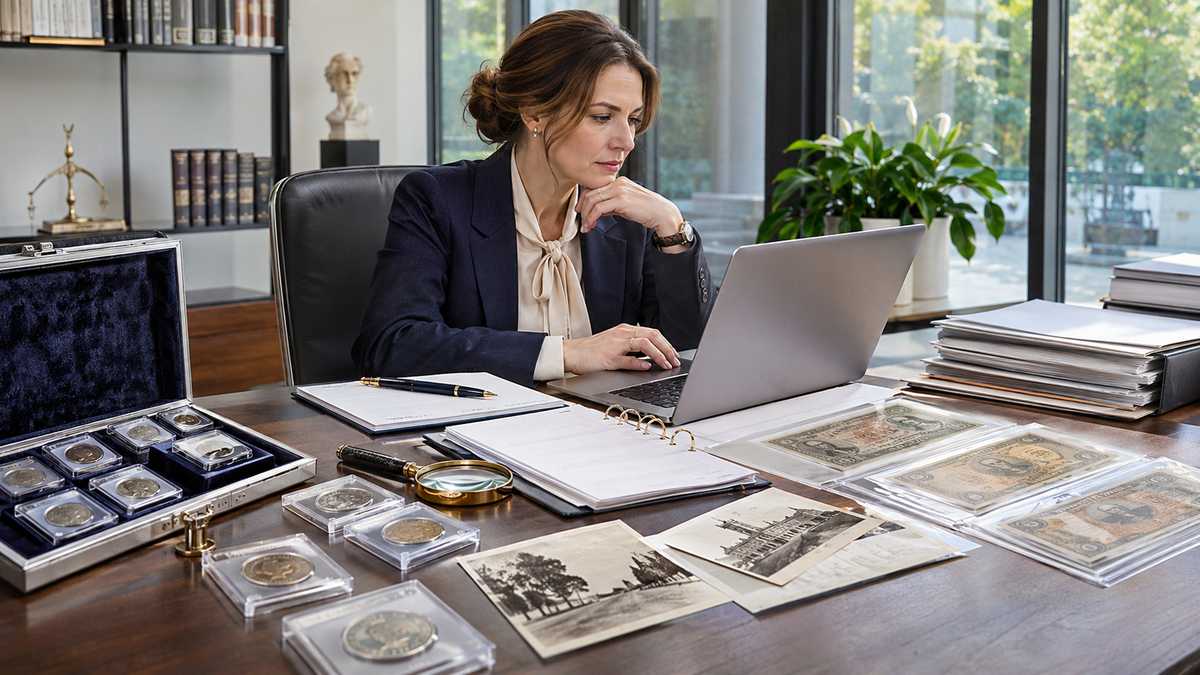
The National Association of Insurance Commissioners (NAIC) recommends maintaining inventories that include photographs, purchase receipts, appraisals, and identifying information. Collectors should apply this approach to individual coins and banknotes, especially valuable specimens.
What Should a Collection Inventory Include?
- Detailed descriptions, including denomination, date, and issuing country.
- Purchase dates, prices, and available receipts.
- Professional grading reports and authentication numbers.
- Clear photographs showing important identifying features.
- Current appraised values and supporting sales information.
Professional numismatists can provide assessments based on condition and comparable market transactions. Digital copies of important records should also be stored securely, preferably separately from the physical collection.
Step 3: Compare Standard Property Insurance With Collectibles Coverage
Many collectors assume their homeowners insurance automatically protects valuable currency collections. However, standard property policies may impose special limits on coins, money, and other collectibles.
The Insurance Information Institute (III) explains that valuable possessions may require scheduled personal property coverage or a separate insurance policy. These arrangements can provide broader protection than standard household coverage.
Specialized collectibles insurance may offer protection against theft, accidental damage, and certain other losses. Coverage during transportation or exhibitions may also be available, depending on the insurer.
Before selecting a policy, collectors should compare premiums, deductibles, covered events, and maximum compensation amounts. The least expensive option may provide insufficient protection for an unusually valuable collection.
Step 4: Examine Exclusions, Limits, and Valuation Methods
Insurance coverage is never unlimited. Each policy specifies situations where compensation may be restricted or unavailable.
Collectors should check whether their policies exclude gradual deterioration, improper storage, unexplained disappearance, or damage caused by inadequate packaging. Natural disasters also require attention because certain events, particularly flooding, may need separate coverage.
The NAIC advises policyholders to understand how insurance contracts calculate compensation. Depending on the policy, payments may involve actual cash value, replacement cost, or an agreed valuation arrangement.
These differences matter when an insured coin becomes difficult to replace. A collector should request written clarification about how the insurer would determine compensation for a rare specimen with limited comparable sales.
Step 5: Understand How Insurance Claims Are Processed
When a collection experiences theft or damage, the claims process determines whether compensation is available. Accurate documentation helps insurers establish ownership, confirm the reported loss, and assess the requested payment.
The NAIC recommends notifying insurers promptly, photographing damage, and maintaining detailed records. For collectible currency, professional assessments may also be necessary to determine whether restoration is possible or whether damage has reduced market value.
What Happens After a Claim Is Submitted?
Although procedures vary, claims generally involve several administrative activities:
- Registering the claim and confirming policy details.
- Collecting photographs, appraisals, and ownership records.
- Reviewing damage reports and independent assessments.
- Checking exclusions, deductibles, and coverage limits.
- Determining eligible compensation and processing payment.
Specialized insurance administration providers may assist with data entry, document classification, customer communication, and records management. These support activities can improve administrative consistency, while authorized insurance personnel remain responsible for coverage decisions.
Collectors should retain copies of all submitted materials and correspondence. Clear records can help resolve discrepancies involving item descriptions, ownership, or reported valuations.
Understanding the financial consequences of denied insurance claims also highlights why accurate documentation and careful policy reviews matter. Missing records, valuation disputes, or misunderstood coverage conditions can complicate claims and leave collectors facing unexpected financial losses.
Step 6: Review Collection Values and Improve Storage Security
Currency collections rarely remain unchanged. New acquisitions, changing market demand, and updated grading assessments can affect their overall value.
The NAIC recommends reviewing insurance needs periodically. Collectors should reassess coverage after major purchases or significant changes in estimated collection values.
Physical protection is equally important. The Smithsonian National Museum of American History has documented its use of protective holders and archival storage materials to preserve numismatic objects.
Private collectors can follow similar preservation principles by using suitable coin holders, archival-quality banknote sleeves, controlled storage conditions, and secure safes. Valuable collections may also benefit from professional storage facilities.
Regular inspections can identify moisture, packaging deterioration, or other problems before extensive damage develops. Insurance should complement these preventive measures rather than replace them.
Protecting Financial Value Through Preparation
Insuring rare coins and banknotes requires more than purchasing a policy. Collectors need reliable valuations, accurate ownership records, suitable coverage, and an understanding of claims requirements.
Professional appraisals and organized documentation can reduce uncertainty when losses occur. Meanwhile, secure storage and periodic policy reviews help address changing risks.
Ultimately, insurance provides financial protection only within its stated terms. Collectors who understand exclusions, compensation methods, and documentation requirements are better prepared to protect their investments while preserving historically significant currency for future generations.